
Imagine filing a car insurance claim and getting paid before you even hang up the phone. Or buying crop insurance that pays out automatically the moment a satellite confirms a drought hit your field. This isn’t science fiction anymore. It is what Blockchain insurance platforms are making possible right now.
For decades, the insurance industry has been stuck in the past. Paperwork piles up, claims take weeks to process, and fraud costs everyone billions. Traditional insurers rely on heavy bureaucracy to manage risk, which drives up costs for you, the policyholder. But blockchain technology-specifically through smart contracts and decentralized ledgers-is tearing down those walls. In 2026, we are seeing a shift from slow, opaque systems to fast, transparent, and automated networks.
This article breaks down exactly how these platforms work, why they matter to you, and who is leading the charge. We will look at the real-world benefits, the current limitations, and what the future holds for this rapidly growing sector.
What Are Blockchain Insurance Platforms?
At its core, a blockchain insurance platform is a digital system that uses distributed ledger technology to handle insurance policies, claims, and payments without relying on a central authority like a traditional bank or insurer. Instead of storing data in one company’s server, the information is spread across many computers (nodes), making it nearly impossible to hack or alter.
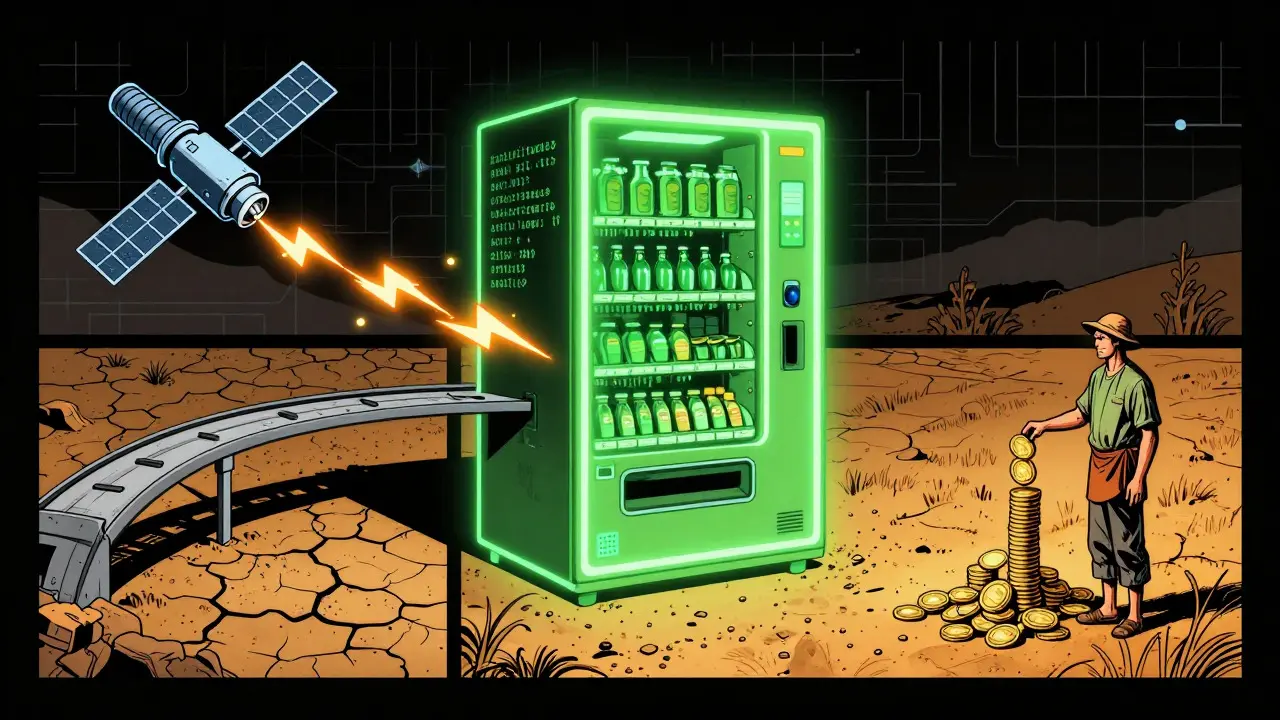
The magic happens with smart contracts, which are self-executing codes stored on the blockchain. Think of a smart contract as a digital vending machine. You put in your premium, and if specific conditions are met-like a flight delay confirmed by an oracle network-the machine automatically dispenses your payout. No claims adjuster needed. No waiting room. No dispute over whether the event actually happened.
This model emerged around 2016-2017, shortly after Ethereum introduced smart contract capabilities. Early pioneers saw that insurance is fundamentally about trust and risk-sharing, two things blockchain handles exceptionally well. Today, platforms like Nexus Mutual and InsurAce allow users to buy coverage for cyber risks, DeFi protocol failures, and more, all peer-to-peer.
Why the Shift? The Problems Blockchain Solves
Traditional insurance is broken in several key ways. Let’s look at the numbers:
- Slow Claims Processing: On average, settling a claim takes 7 to 14 days. With blockchain, verified claims can be settled in under 24 hours, often within minutes for parametric products.
- High Administrative Costs: Traditional insurers spend 20-30% of premiums on administration and intermediaries. Blockchain platforms reduce this to 8-12% by cutting out the middleman.
- Fraud Vulnerability: Fraudulent claims cost the industry billions annually. Blockchain’s immutable audit trail reduces fraud by an estimated 30-40%, according to recent case studies.
- Lack of Transparency: Policyholders often don’t know how their premiums are used or how decisions are made. Blockchain provides a public, verifiable record of every transaction.
These aren’t just theoretical improvements. They are driving massive growth. The blockchain insurance market is projected to explode from $2.74 billion in 2025 to $82.56 billion by 2033, growing at a compound annual rate of 53%. Why? Because consumers want speed, lower costs, and fairness.
How It Works: The Technology Behind the Coverage
To understand blockchain insurance, you need to grasp three technical components:
- Distributed Ledger: Every policy and claim is recorded on a shared database. Once written, it cannot be changed. This creates a single source of truth for all parties involved.
- Smart Contracts: These are the rules of the policy written in code. For example, "If wind speed exceeds 100 mph in Location X, pay $Y to Policyholder Z." When the condition is met, the contract executes automatically.
- Oracle Networks: Blockchains can’t see the outside world. That’s where oracles come in. Services like Chainlink fetch real-world data (weather reports, flight statuses, stock prices) and feed it into the smart contract to trigger payouts.
Most platforms operate on public blockchains like Ethereum, though some use permissioned networks like Hyperledger Fabric for enterprise solutions. The choice depends on the need for transparency versus privacy. Public chains offer full visibility, while private chains give companies more control over who can access the data.
Key Players in the Market
The landscape is crowded but evolving. Here are some of the most notable platforms shaping the industry in 2026:
| Platform | Launched | Primary Focus | Key Feature |
|---|---|---|---|
| Nexus Mutual | 2017 | DeFi & Cyber Risks | Peer-to-peer mutual model |
| InsurAce | 2021 | DeFi Protocol Coverage | Cross-chain interoperability |
| Ensuro | 2020 | Parametric Insurance | Automated weather-based payouts |
| OpenCover | 2019 | Travel & Life | Tokenized risk pools |
| Uno Re | 2021 | Reinsurance | Decentralized reinsurance marketplace |
Nexus Mutual stands out as a pioneer, having built a community-driven mutual insurance pool where members share risk directly. InsurAce focuses heavily on protecting decentralized finance protocols against hacks and exploits. Meanwhile, Ensuro specializes in parametric insurance, offering instant payouts for events like natural disasters based on objective data triggers.
Benefits vs. Limitations: A Realistic View
Blockchain insurance is not a silver bullet. While it offers significant advantages, it also faces real challenges that limit its widespread adoption today.
The Benefits:
- Speed: Parametric insurance can pay out in minutes. Imagine a farmer receiving funds immediately after a drought is confirmed, rather than waiting months for an assessment.
- Cost Efficiency: Lower administrative overhead means lower premiums for customers.
- Inclusivity: People without traditional banking access can participate in global risk pools using cryptocurrency.
- Fraud Reduction: Immutable records make it hard to fake claims or double-dip.
The Limitations:
- Complexity: Only about 15% of insurance claims qualify for full automation. Complex cases involving human judgment (like personal injury) still require manual review.
- Scalability: Ethereum processes only 15-30 transactions per second. While upgrades like Dencun have reduced costs by 90%, throughput remains a bottleneck compared to Visa or Mastercard.
- Regulatory Uncertainty: As of early 2025, only 28 jurisdictions have clear frameworks for blockchain insurance. This creates legal gray areas for both providers and users.
- Integration Challenges: Connecting new blockchain systems with legacy insurance software is difficult and expensive, consuming 35-40% of project resources.
The Future: What to Expect in 2026 and Beyond
We are currently in the early stages of adoption. About 22% of large insurers have implemented at least one blockchain application, with property and casualty leaders leading the way. Asia-Pacific dominates with 37% of global deployments, driven by supportive regulations in Singapore and South Korea. Europe is growing fastest, with a 45% year-over-year increase in pilots.
Several trends will shape the next few years:
- AI Integration: Combining AI with smart contracts will allow platforms to handle more complex claims that currently require human adjusters.
- IoT Convergence: By 2025-2026, parametric insurance will expand beyond weather to include health, auto, and home insurance, triggered by data from connected devices like wearables and smart cars.
- Cross-Chain Solutions: Platforms like InsurAce and Uno Re are testing interoperability tools to connect different blockchain networks, creating a unified global market.
- Regulatory Clarity: Frameworks like the EU’s MiCA are setting standards that other regions may follow, reducing uncertainty for investors and consumers.
Experts predict mainstream adoption between 2027 and 2029, once these technologies solve specific pain points better than traditional systems at scale. Until then, blockchain insurance will likely coexist with traditional models, serving niche markets first before becoming the norm.
Getting Started: Tips for Users and Businesses
If you’re curious about trying blockchain insurance, start small. Look for platforms with strong reputations, clear documentation, and active communities. Check if they use reputable oracle networks like Chainlink for data verification. For businesses, consider pilot projects focused on high-volume, low-complexity claims like travel delays or freight insurance. These offer the quickest return on investment and lowest implementation risk.
Remember, education is key. Staff training typically requires 80-120 hours to become proficient with blockchain systems. Invest in learning Solidity basics or hire developers experienced in Rust and Go. And always consult legal experts familiar with both insurance law and blockchain regulations in your jurisdiction.
Is blockchain insurance safe?
Yes, but with caveats. The underlying blockchain technology is highly secure due to cryptographic hashing and decentralization. However, risks exist in smart contract bugs, oracle manipulation, and user error (e.g., losing private keys). Always choose audited platforms and diversify your risk exposure.
What is parametric insurance?
Parametric insurance pays out when a predefined parameter (like wind speed or earthquake magnitude) is reached, regardless of actual financial loss. It’s ideal for blockchain because the trigger is objective and easily verifiable via oracles, enabling instant automated payouts.
Can I replace my traditional car insurance with blockchain insurance?
Not yet. Most blockchain platforms focus on niche areas like cyber risk, DeFi, travel, or parametric weather coverage. Comprehensive auto or life insurance requiring complex liability assessments is still dominated by traditional insurers. Hybrid models are emerging, but full replacement is unlikely before 2030.
Who regulates blockchain insurance platforms?
Regulation varies by region. The EU has established guidelines under MiCA, while the US operates on a state-by-state basis. Many platforms operate in regulatory gray zones, so users should check local laws. Industry bodies like The Geneva Association are pushing for standardized global frameworks.
How much does it cost to build a blockchain insurance platform?
A minimum viable product (MVP) typically costs between $500,000 and $1.2 million, taking 6-9 months to develop. Costs include smart contract development, oracle integration, security audits, and compliance setup. Ongoing maintenance and marketing add further expenses.
What role do oracles play in blockchain insurance?
Oracles bridge the gap between blockchains and real-world data. They provide verified external information (e.g., weather data, flight status) to smart contracts, triggering automatic payouts. Without reliable oracles, smart contracts cannot execute accurately, making them critical infrastructure for parametric insurance.
Are there tax implications for blockchain insurance payouts?
Tax treatment depends on your jurisdiction and the type of insurance. Generally, indemnity payouts (replacing lost value) are not taxable, but profit-generating investments might be. Since blockchain transactions are transparent, reporting is easier, but consulting a tax professional familiar with crypto assets is recommended.
Subhash Kashyap Dm
August 9, 2026 AT 21:32smart contracts are just code and code has bugs the whole premise of trustless systems is a fallacy because you still have to trust the oracle network which is basically a centralized point of failure wrapped in crypto jargon to make it sound decentralized. nexus mutual and insurace are just ponzi schemes with better marketing materials designed to extract liquidity from retail investors who dont understand solidity vulnerabilities. the regulatory gray areas mentioned are not accidents they are deliberate loopholes exploited by offshore entities to avoid solvency requirements that traditional insurers adhere to under strict state supervision. do not put your life savings into these digital vending machines because when the oracle fails or the smart contract gets drained by a reentrancy attack there is no fdic insurance and no recourse for the average joe.
Kat Bennett
August 10, 2026 AT 23:59I actually think this is such a fascinating development for the industry, especially considering how frustrating it has always been to deal with traditional claims processing where you feel like you are shouting into the void for weeks on end while waiting for an adjuster to get back to you about something as simple as a fender bender. The idea that a farmer could receive funds immediately after a drought is confirmed by satellite data rather than waiting months for a physical assessment really speaks to the potential for genuine humanitarian aid through technology, and it makes me wonder if we will see similar applications in disaster relief efforts globally where speed is literally a matter of life and death for affected communities.
Candice Cornett
August 12, 2026 AT 19:48another day another tech bro solution looking for a problem that doesnt exist because the real issue with insurance isnt bureaucracy its risk pooling which requires massive capital reserves that blockchain startups simply do not have. calling it transparent is laughable when the code is written by anonymous devs and audited by firms that get paid by the very platforms they are auditing creating a conflict of interest that would make a wolf of wall street blush. the market projection numbers are pure fiction generated by vc firms trying to justify their valuations before the inevitable crash wipes out everyone who bought in during the hype cycle.
Jack Delasquez
August 13, 2026 AT 22:59this is gonna change evrything man!! i cant wait to buy my car insurance on the blockchain and get paid instantly when i crash lol. why are people so negative about progress?? its just code dude lets embrace the future and stop worrying about bugs because innovation always comes with a few hiccups but the benefits are clear right?? lower costs faster payouts what more do u want??
Harman Singh
August 15, 2026 AT 01:28why does this article make me feel so empty inside? all this talk of efficiency and transparency but nobody mentions the human cost of automation or how many adjusters are going to lose their jobs to some algorithm running on ethereum. i just feel sad reading this because it feels cold and sterile like the world is losing its soul to lines of code that dont care about our struggles or our families. maybe we should focus on helping people instead of optimizing transactions for profit margins that only benefit the top 1%.
Qolbina Islami
August 15, 2026 AT 19:46THIS IS A THREAT TO NATIONAL SECURITY!!! The fact that Asian jurisdictions like Singapore and South Korea are leading the charge proves that the West is falling behind in the global economic war! We need American companies to dominate this space immediately or we will be subservient to foreign blockchains! The EU's MiCA framework is just another way for bureaucrats to stifle American innovation! Wake up people! Blockchain insurance must be made in America for Americans!
SUBHAM CHOUDHURY
August 15, 2026 AT 21:33Hey everyone, let's keep the energy positive here. It's great to see different perspectives on this topic. While some concerns about regulation are valid, remember that every new technology faces growing pains. Let's support each other as we learn more about how these platforms can benefit us all. Keep an open mind and stay curious about the possibilities ahead.
Joy Kwant
August 16, 2026 AT 10:09i am so tired of hearing about blockchain saving everything. it never saves anything it just creates more waste and complexity. the moral decay of relying on algorithms for basic human needs like security is disturbing. we used to have community based support systems now we have tokenized risk pools. disgusting. i bet the founders are living in mansions while regular people struggle to understand how to use a wallet.
amy miranda
August 17, 2026 AT 00:07The sheer arrogance of assuming that a piece of software can replace centuries of actuarial science and legal precedent is breathtakingly stupid. These platforms are unregulated gambling dens disguised as financial instruments, and anyone who puts money into them without understanding the underlying cryptographic risks is merely volunteering to be fleeced by sophisticated criminals hiding behind pseudonyms. The notion that 'transparency' solves fraud is laughable when the source of truth relies on third-party oracles that can be bribed or hacked, rendering the entire immutable ledger meaningless if the input data is corrupted from the start.
Pernelia Wahkan
August 18, 2026 AT 07:22It is quite intriguing how the integration of AI with smart contracts might eventually bridge the gap between rigid automated rules and the nuanced reality of complex claims. I often find myself wondering if the current limitation regarding the 15% automation rate is truly a technical barrier or simply a lack of creative coding solutions that haven't been discovered yet. Perhaps the key lies in developing hybrid models where AI acts as a preliminary filter for straightforward cases, allowing human adjusters to focus solely on the intricate disputes that require empathy and contextual understanding, thereby creating a more efficient and humane system overall.
Billy Cunningham
August 19, 2026 AT 11:05too complicated 🤯 just want my money back when i crash my car 😩
Ed Wallace
August 21, 2026 AT 00:01One must consider the philosophical implications of shifting trust from institutions to algorithms. Is a smart contract truly 'trustless' if we still rely on the integrity of the developers who wrote it and the oracles that feed it data? This paradox suggests that we are not eliminating trust but rather redistributing it to a new class of technical elites who hold the keys to the kingdom. It raises profound questions about agency and autonomy in a digitized society.
Joshua Hofford
August 22, 2026 AT 04:45Man, this stuff is wild! I mean, imagine being a farmer in India and getting paid instantly when the rains fail. That kind of tech could really help people who are left out of the traditional banking system. It's cool to see how different cultures are adopting this, especially in Asia where mobile tech is huge. Let's hope it spreads everywhere and helps folks worldwide!
Marcia Albert
August 22, 2026 AT 19:56I suppose it's interesting to watch this unfold like a slow-motion car crash that somehow becomes a feature. The colorful language of 'tearing down walls' is nice but walls usually serve a purpose like keeping out vandals or maintaining structural integrity. Still, I guess if the vending machine analogy holds water then maybe we'll all be sipping digital sodas soon enough.
Emma Smith
August 24, 2026 AT 06:53the paradigm shift is undeniable yet the epistemological crisis remains unresolved because how do we verify the verification mechanism itself without falling into infinite regress of meta-oracles feeding data to sub-oracles until we reach a singular point of truth that is inevitably compromised by human bias or mechanical failure at the hardware level thus rendering the entire distributed ledger a mere facade of decentralization masking a highly centralized control structure.
Ed Mitchell
August 26, 2026 AT 04:35The narrative presented herein is a carefully constructed illusion designed to pacify the masses with promises of technological utopia while obscuring the draconian surveillance capabilities inherent in immutable ledgers. Every transaction recorded forever means every movement of wealth is tracked by unseen eyes, likely those of shadowy cabals seeking to consolidate power under the guise of 'innovation'. One must remain vigilant against this digital panopticon that threatens individual liberty and privacy rights essential to a free society.